S&P Global Ratings has lifted Zambia out of the CCC bracket for the first time since 2019. The agency likes the growth and the debt deal. It is less impressed by this year’s budget overrun.
KEY TAKEAWAYS
- S&P Global Ratings upgraded Zambia’s long- and short-term sovereign ratings from CCC+/C to B-/B with a stable outlook on 20 November 2026. It is the first time S&P has rated Zambia B- since August 2019.
- S&P expects growth to average 5.5% a year from 2026 to 2029, against 3.6% over the previous decade, helped by copper prices and recovering farm and power output.
- Creditors covering about 94% of the US$13.3 billion restructuring perimeter have agreed deals in principle, by S&P’s count, and more than 60% is fully executed. The Treasury puts the agreed share at about 96%.
- The 2026 fiscal deficit is now expected at 5.9% of GDP, roughly double the 2.9% target. S&P expects consolidation to restart in 2027.
- B- is still six notches below investment grade. The test now is whether cheaper credit reaches firms and households through investment, exports and jobs.
Zambia’s sovereign credit rating is now B- at S&P Global Ratings, up one notch from CCC+, with a stable outlook. The agency announced the upgrade on Friday, 20 November 2026, citing supportive copper prices, faster economic growth and steady progress in restructuring the debt Zambia defaulted on in 2020. The short-term rating moved from C to B.
The move puts S&P level with Fitch Ratings, which has rated Zambia B- since November 2025, and one notch above Moody’s, which raised Zambia to Caa1 on 30 October.
What exactly did S&P change?
S&P raised its long-term foreign and local currency ratings on Zambia to B- from CCC+, and its short-term ratings to B from C. The outlook is stable, which means the agency does not expect to move the rating again in either direction over roughly the next year unless something changes sharply.
The distinction matters. A CCC rating says a borrower depends on favourable conditions to keep paying. A B rating says it can currently pay but remains vulnerable to a bad shock. S&P last rated Zambia B- in August 2019, before it cut the country to CCC+, then to selective default in October 2020 when Lusaka missed a Eurobond coupon.
Why did S&P upgrade Zambia?
Faster growth, carried by copper
S&P projects real GDP growth averaging 5.5% a year between 2026 and 2029. Over the preceding decade the economy averaged 3.6%. The IMF’s own forecast for 2026 is 5.6%, which it attributes to strong agricultural production, mining activity and exports.
Copper does most of the lifting. It makes up more than 70% of Zambia’s goods exports, and output is forecast at around 930,000 tonnes this year. S&P expects copper prices to ease from recent highs, which is why its growth average for 2026 to 2029 is lower than this year’s figure.
A debt restructuring that is nearly finished
By S&P’s count, Zambia has agreements in principle covering about 94% of the US$13.3 billion inside its restructuring perimeter, and more than 60% has been fully executed. The Ministry of Finance and National Planning, in its statement welcoming the upgrade, put the agreed share at approximately 96%. The gap probably reflects different cut-off dates or definitions. Either way, the remaining talks are expected to conclude in 2027.
Zambia has also cleaned up its Eurobond profile. A tender offer in May 2026 retired the 2053 notes at 75.20 cents on the dollar, partly funded by a US$600 million African Development Bank loan, with savings committed to the electricity grid. That leaves 2033 as Zambia’s only remaining Eurobond maturity.
Policy continuity and a new IMF programme
S&P points to continuity after President Hakainde Hichilema’s re-election in August. It also cites the 9 October staff-level agreement with the IMF on a 36-month Extended Credit Facility worth US$1.472 billion. That deal still needs approval from the IMF Executive Board, which the Fund’s mission chief, Edward Gemayel, has said is likely in December.
The less flattering parts of the report
The upgrade comes with a warning about 2026. S&P now expects this year’s fiscal deficit to reach 5.9% of GDP, against an original target of 2.9%. The overrun came from spending around the August election and larger purchases for the strategic food reserve. Fuel tax relief also cost revenue. S&P expects consolidation to resume in 2027, with the deficit narrowing to 3.5% of GDP by 2029. The government’s own targets are tighter, at 3% in 2027.
General government debt is also still heavy, averaging about 83.2% of GDP over S&P’s forecast period. S&P lists four risks to watch:
- El Niño, which could cut crop yields and hydropower. Hydro supplies more than 80% of Zambia’s electricity.
- Inflation pressure when the suspension of fuel levies ends on 1 December.
- The risk of post-election unrest.
- The debt stock itself.
S&P says it could raise the rating further if Zambia builds foreign reserves faster or cuts debt to GDP more steeply than expected. It could cut the rating if the remaining debt talks stall or a severe drought damages the public finances.
Where Zambia stands with the three agencies
| Agency | Current rating | Outlook | Last action | Previous rating |
|---|---|---|---|---|
| S&P Global Ratings | B- / B | Stable | 20 November 2026 | CCC+ / C (since November 2025) |
| Fitch Ratings | B- | Stable | 28 November 2025 | Restricted Default |
| Moody’s Ratings | Caa1 | Positive | 30 October 2026 | Caa2 |
Moody’s Caa1 sits on the same rung as S&P’s old CCC+, so Moody’s is now one notch behind the other two. Its positive outlook signals that it may close that gap.
How far is Zambia from investment grade?
Six notches. On S&P’s scale, the steps from B- to the lowest investment grade rating, BBB-, are B, B+, BB-, BB, BB+ and then BBB-. Zambia is now back in the same broad band as many frontier economies that borrow on international markets. It is not close to the top of it.
What does the upgrade mean for businesses and investors?
For foreign portfolio investors, a B- rating widens the pool of funds allowed to hold Zambian debt. Some mandates exclude anything rated in the CCC range. That can, over time, lower the yield Zambia pays on its 2033 Eurobond and on any new borrowing.
Zambian banks and large companies usually cannot borrow abroad more cheaply than their government, because agencies rarely rate a company above its sovereign. A higher sovereign ceiling gives firms such as mining contractors, banks and exporters more room to raise foreign funding on better terms. It also helps with letters of credit and trade finance, where foreign banks price Zambian risk partly off the sovereign rating.
None of this happens automatically. Domestic lending rates are set mainly by the Bank of Zambia’s policy rate, government borrowing at home and banks’ own risk appetite. A rating change helps only if the Treasury uses the room to borrow less from local banks and leaves more credit for private borrowers, a point the Economics Association of Zambia made when backing the IMF deal.
What does it mean for ordinary Zambians?
A credit rating does not put money in anyone’s pocket on Monday morning. Its effect on households runs through two slower channels.
The first is the budget. Every kwacha the government saves on interest is a kwacha it can spend on salaries, medicines, schools or the grid, or leave in the economy through lower borrowing. Interest costs have been one of the largest items in recent budgets, so cheaper refinancing matters.
The second is jobs. If better ratings bring in more foreign investment in mining, energy and agriculture, the payoff for households is employment and supplier contracts. The Ministry of Finance said as much in its own statement: improved creditworthiness has to turn into productive investment, exports, jobs and higher household incomes.
In the short term, households are more likely to feel the end of the fuel levy suspension on 1 December than anything in S&P’s report.
What did the government say?
Finance and National Planning Minister Dr Situmbeko Musokotwane welcomed the upgrade as a signal to investors, financial institutions and development partners. The Ministry said the expected IMF programme, subject to approval, would support macroeconomic stability, debt sustainability and delivery of the 2027 National Budget, the Ninth National Development Plan and the Grow Zambia Agenda. It said further gains would depend on continued fiscal discipline, stronger economic performance and measurable development results.
What happens next?
- 1 December 2026: the fuel levy suspensions expire, which S&P flags as an inflation risk.
- December 2026: the IMF Executive Board is expected to consider the US$1.472 billion Extended Credit Facility.
- 2026/27 rainy season: rainfall will decide how much El Niño affects maize output and Kariba and Kafue Gorge water levels.
- 2027: the remaining debt restructuring talks are expected to close, and the 2027 Budget is due to start cutting the deficit.
The upgrade gives Zambia credit for the restructuring and for growth. The rating will move again only if 2027’s deficit actually falls. That is the number to watch.
Sources: S&P Global Ratings research update on Zambia, 20 November 2026, as reported by Investing.com; Ministry of Finance and National Planning statement, 21 November 2026; IMF staff-level agreement press release, 9 October 2026; Fitch Ratings and Moody’s Ratings rating actions.
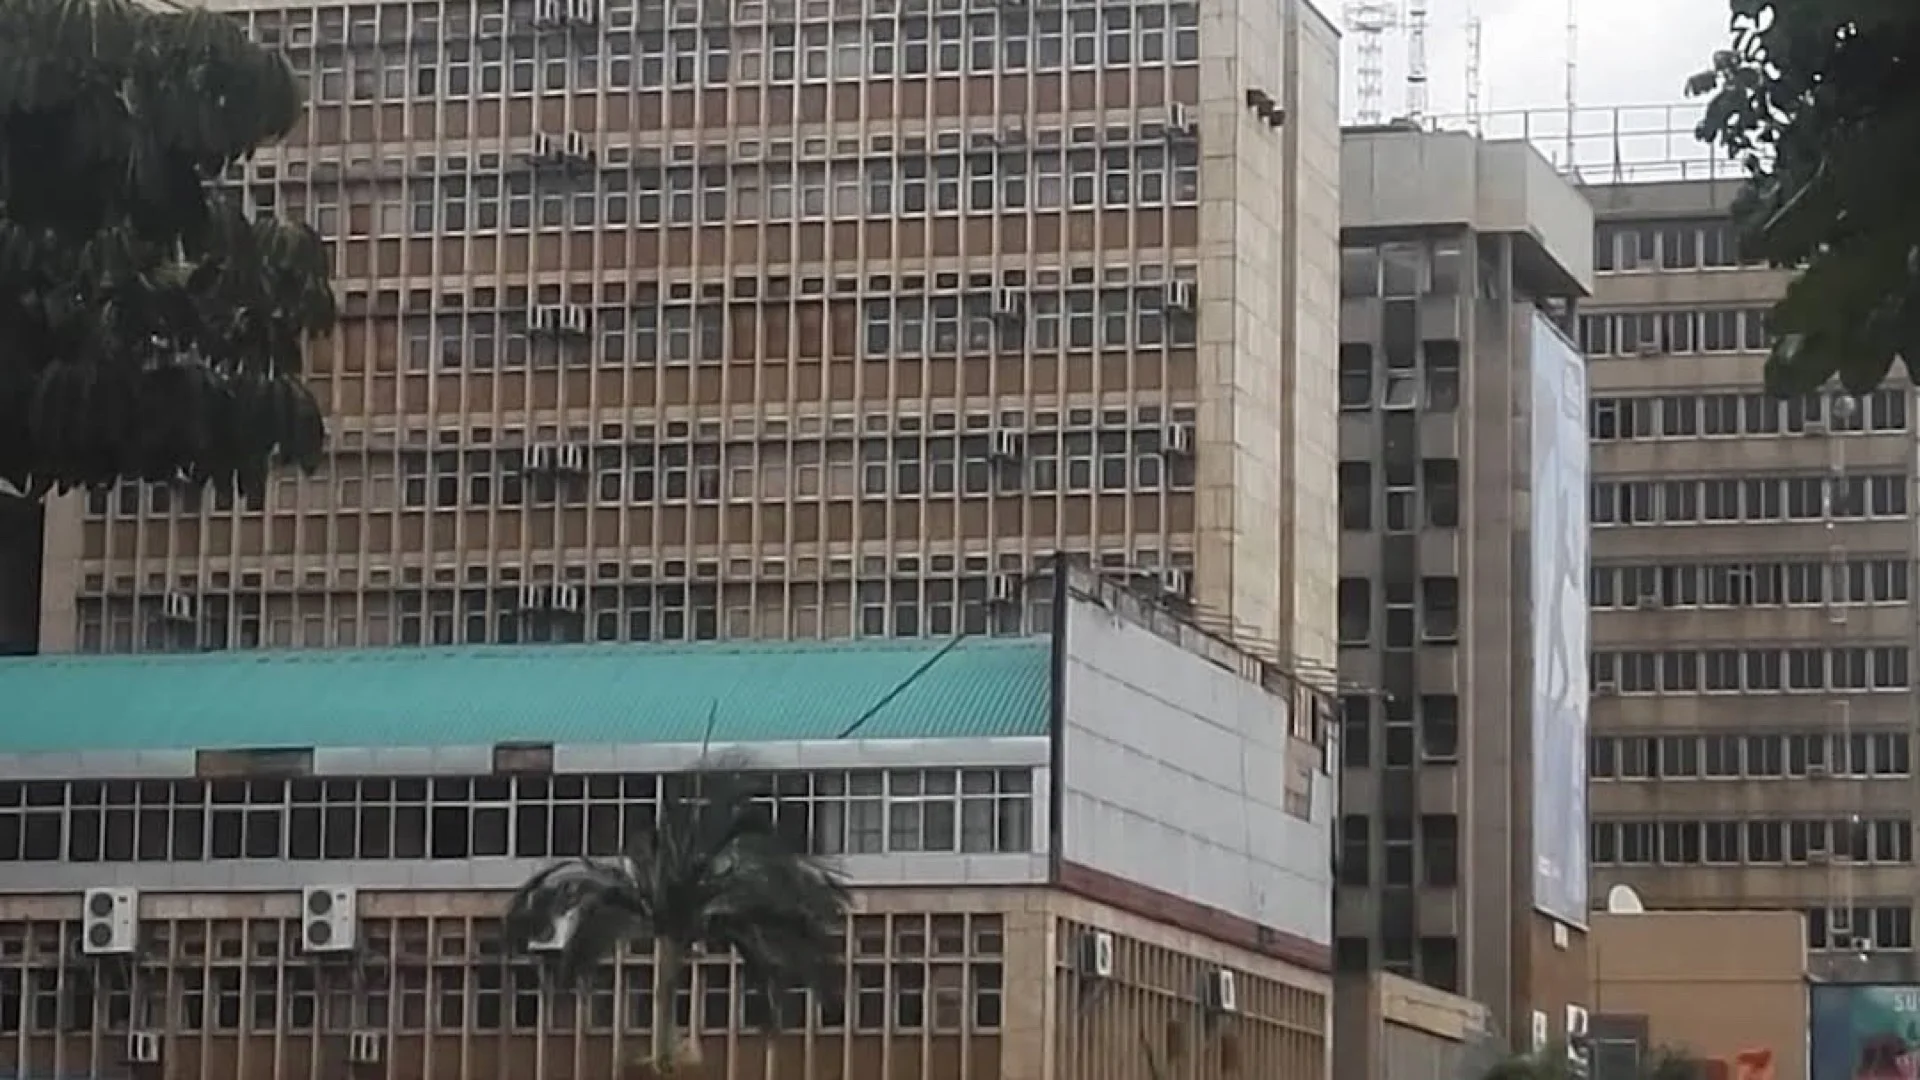
Featured photo: Bank of Zambia headquarters, Lusaka. Photo by Yameliode via Wikimedia Commons, CC BY 4.0. Cropped and converted by The Zambian Economist.
Related coverage
- Moody’s Lifts Zambia to Caa1 Days Before the 2027 Budget
- Zambia’s external debt falls 5% as Eurobond savings go to the power grid
- Mineral Wealth Is No Reason to Shun the IMF, Says Musokotwane
- Budget 2027: A Bigger Envelope With Only K6.9 Billion of Room
- Grow Zambia Agenda: What It Would Take to Double Zambia’s Economy by 2031
- Zambia Economic Dashboard and Doing Business in Zambia
- Business Directory | Events | Get The Ledger, our free weekly briefing
WARNING! All rights reserved. This material and all other digital content on this website may not be reproduced, published, broadcast, rewritten, or redistributed, in whole or in part, without the prior express permission of The Zambian Economist. Where permission is granted, the content must be clearly credited to “The Zambian Economist,” with “www.zambianeconomist.com” prominently displayed.
WhatsApp: +260775574228 | Email: info@zambianeconomist.com
© 2026 The Zambian Economist.